Chautauqua Lake real estate insights from Rick and Julia McMahon, Broker Associates and Partners at Real Estate Advantage. Explore lakefront homes, vacation properties, second homes, local housing market trends, and community news. Proudly serving Chautauqua and Cattaraugus Counties since 1992.
When a home is listed “as is,” sellers and buyers can read those two words very differently. A seller may see a few projects the next owner can tackle over time. A buyer may start adding up repair costs before they’ve even finished the showing.
This month’s Lighter Side article takes a look at what sellers expect and how buyers actually react.
If you’re thinking about selling and wondering which repairs are worth doing before you list, give us a call, text, or email. We can walk through what buyers are likely to notice and what you can leave for the next owner.
As we move into the fall real estate season, we're seeing some interesting changes in our local housing markets. Home prices remain relatively strong, but increasing inventory and longer selling times are giving buyers more choices.
Here's a look at September's numbers, how they compare with last year, and what we're seeing in each county.
📍 CHAUTAUQUA COUNTY
📊 SEPTEMBER 2026 vs. SEPTEMBER 2025
🏠 New Listings: 123 ⬆️ 2.5%
✍️ Pending Sales: 79 ⬇️ 19.4%
🔑 Closed Sales: 101 ⬆️ 12.2%
💲 Median Sale Price: $208,400 ⬇️ 0.8%
💵 Average Sale Price: $263,344 ⬆️ 2.1%
⏳ Days on Market: 37 ⬆️ 37.0%
🏷️ List Price Received: 96.3% ⬇️ 4.1%
📦 Homes for Sale: 356 ⬆️ 29.5%
📈 Months of Inventory: 4.5 ⬆️ 32.4%
📅 2026 YEAR-TO-DATE vs. 2025
🏠 New Listings: 1,105 ⬆️ 4.7%
✍️ Pending Sales: 762 ⬇️ 4.4%
🔑 Closed Sales: 699 ⬆️ 5.4%
💲 Median Sale Price: $184,000 ⬆️ 12.5%
💵 Average Sale Price: $228,005 ⬇️ 0.5%
⏳ Days on Market: 45 ➖ No Change
🏷️ List Price Received: 97.1% ➖ No Change
🔎 OUR TAKE — CHAUTAUQUA COUNTY
The Chautauqua County housing market continues to show solid overall strength, but the balance is gradually shifting toward buyers.
September closed sales increased 12.2%, and year-to-date sales are up 5.4%. The median sale price is also up an impressive 12.5% year-to-date, indicating that the market continues to support strong selling prices.
However, the bigger story is inventory. The number of homes available for sale has jumped nearly 30%, and months of inventory has increased to 4.5 months. At the same time, September pending sales dropped 19.4%, suggesting buyer activity may be slowing as we head into the final quarter of the year.
Homes are also taking longer to sell, and sellers received an average of 96.3% of their most recent asking price in September.
Bottom line: Chautauqua County remains a healthy market, but buyers have more choices and greater negotiating opportunities. For sellers, accurate pricing, property condition, and strong marketing are becoming increasingly important. Well-priced properties in desirable locations can still attract considerable interest.
📍 CATTARAUGUS COUNTY
📊 SEPTEMBER 2026 vs. SEPTEMBER 2025
🏠 New Listings: 78 ⬇️ 12.4%
✍️ Pending Sales: 54 ⬇️ 12.9%
🔑 Closed Sales: 55 ⬇️ 22.5%
💲 Median Sale Price: $179,000 ⬇️ 0.6%
💵 Average Sale Price: $214,028 ⬇️ 4.5%
⏳ Days on Market: 51 ⬆️ 41.7%
🏷️ List Price Received: 95.6% ⬇️ 4.3%
📦 Homes for Sale: 263 ⬆️ 7.8%
📈 Months of Inventory: 4.8 ⬆️ 9.1%
📅 2026 YEAR-TO-DATE vs. 2025
🏠 New Listings: 763 ⬆️ 10.1%
✍️ Pending Sales: 532 ⬆️ 3.1%
🔑 Closed Sales: 485 ⬆️ 2.3%
💲 Median Sale Price: $181,000 ⬆️ 2.8%
💵 Average Sale Price: $220,806 ⬇️ 1.5%
⏳ Days on Market: 58 ⬆️ 7.4%
🏷️ List Price Received: 96.3% ⬇️ 1.0%
🔎 OUR TAKE — CATTARAUGUS COUNTY
Cattaraugus County is showing more noticeable signs of a cooling market, particularly in September.
Closed sales dropped 22.5% compared with September 2025, while pending sales declined 12.9%. Homes also took considerably longer to sell, with days on market increasing 41.7% to 51 days.
Despite the slower September activity, the year-to-date numbers tell a somewhat more encouraging story. Closed sales remain 2.3% ahead of last year, and the median sale price has increased 2.8%.
Inventory has risen to 4.8 months, placing the county closer to a balanced market. Sellers received an average of 95.6% of their most recent asking price in September, suggesting buyers are negotiating more aggressively.
Bottom line: Buyers are becoming more selective, and sellers can no longer assume their property will sell quickly simply because inventory was tight in previous years. Competitive pricing and good presentation are essential. For buyers, the additional inventory and longer selling times may create opportunities that were harder to find a year or two ago.
🏡 Thinking About Buying or Selling?
The overall numbers tell us where the market is heading, but real estate is local—sometimes right down to the neighborhood, street, or individual property.
Whether you're considering selling, looking to purchase, or simply curious about what your home might be worth in today's market, we'd be glad to provide a complimentary, no-obligation market analysis based on recent sales and current competition.
Just reply to this email or give us a call.
Rick & Julia McMahon Broker Associates & Partners Real Estate Advantage
Serving from Peek'n Peak to Ellicottville and all the lakes in between since 1992.
Source: September 2026 MLS Monthly Market Reports, Activity Overview, Page 2. Data current as of October 10, 2026. Statistics include single-family homes, townhomes, and condominiums.
For More Information On Chautauqua Lake & County Real Estate and Living Visit: chautauqualakehomes.com
The latest numbers are in for Chautauqua and Cattaraugus Counties. Here's a quick look at what happened in August and where the market stands year-to-date.
🏡 CHAUTAUQUA COUNTY
August 2026 vs. August 2025
📋 New Listings: 162 ↓ 6.4% 🤝 Pending Sales: 86 ↓ 25.9% 🏠 Closed Sales: 109 ↑ 6.9% ⏱️ Days on Market: 39 No Change
💰 Median Sale Price:$208,600 ↑ 18.4% 💵 Average Sale Price:$262,128 ↓ 4.4% 📊 Percent of List Price Received: 98.1% ↑ 1.1%
🏘️ Homes for Sale: 363 ↑ 29.6% 📦 Months Supply of Inventory: 4.6 months ↑ 31.4%
📅 YEAR-TO-DATE — 2026 vs. 2025
📋 New Listings: 982 ↑ 5.0% 🤝 Pending Sales: 668 ↓ 4.4% 🏠 Closed Sales: 597 ↑ 4.2% ⏱️ Days on Market: 47 No Change
💰 Median Sale Price:$180,100 ↑ 11.2% 💵 Average Sale Price:$222,183 ↓ 1.1% 📊 Percent of List Price Received: 97.3% ↑ 0.7%
🔎 OUR TAKE — CHAUTAUQUA COUNTY
Chautauqua County continues to show strong home values, with the August median sale price up 18.4% from last year and the year-to-date median up 11.2%.
At the same time, inventory has jumped nearly 30%, with a 4.6-month supply of homes now available. That's giving buyers considerably more choice and moving the market closer to balance.
For sellers, the message is pretty clear: buyers are still buying, but pricing and presentation matter more as inventory increases.
🏡 CATTARAUGUS COUNTY
August 2026 vs. August 2025
📋 New Listings: 94 ↑ 5.6% 🤝 Pending Sales: 65 ↓ 4.4% 🏠 Closed Sales: 71 ↑ 18.3% ⏱️ Days on Market: 43 ↓ 17.3%
💰 Median Sale Price:$190,000 ↑ 8.6% 💵 Average Sale Price:$223,763 ↓ 4.6% 📊 Percent of List Price Received: 98.8% ↑ 1.6%
🏘️ Homes for Sale: 268 ↑ 15.5% 📦 Months Supply of Inventory: 4.8 months ↑ 17.1%
📅 YEAR-TO-DATE — 2026 vs. 2025
📋 New Listings: 684 ↑ 13.2% 🤝 Pending Sales: 479 ↑ 5.5% 🏠 Closed Sales: 425 ↑ 5.5% ⏱️ Days on Market: 59 ↑ 3.5%
💰 Median Sale Price:$181,750 ↑ 3.9% 💵 Average Sale Price:$222,148 ↓ 0.9% 📊 Percent of List Price Received: 96.5% ↓ 0.3%
🔎 OUR TAKE — CATTARAUGUS COUNTY
Cattaraugus County had a solid August. Closed sales increased 18.3%, the median sale price rose 8.6%, and homes sold faster than they did last August.
Year-to-date activity is also ahead of 2025, with closed and pending sales both up 5.5%. Inventory is increasing here as well, with 15.5% more homes for sale than a year ago.
Buyers have more choices, but properly priced homes are still selling.
📊 THE BIG PICTURE
Both counties are showing a similar trend: more inventory, continued sales activity and generally higher median prices.
The days when nearly every property sold quickly regardless of price are behind us. Buyers have more choices and are becoming more selective.
For sellers, price, condition, location and exposure are increasingly important. For buyers, the additional inventory is creating more opportunities and a little more negotiating room.
Thinking about buying or selling? We're always happy to talk about what these numbers mean for your specific property or neighborhood.
Rick & Julia McMahon Broker Associates & Partners Real Estate Advantage
By Kelsey MulveyPublished: Sep 02, 2026 4:18 PM EDT
Fun fact: The United States Postal Service established ZIP codes as an efficient way to sort mail after World War II. These days, a reputation often precedes those five digits. You likely envision big mansions, California sunshine, and binge-worthy teenage drama when you think of 90210, right?
Here’s a quick look at how the residential real estate markets performed in Chautauqua and Cattaraugus Counties in July, along with the year-to-date numbers.
📍 CHAUTAUQUA COUNTY
📊 July 2026 vs. July 2025
🏠 New Listings: 154 ⬆️ 4.1% ✍️ Pending Sales: 102 ⬆️ 4.1% 🔑 Closed Sales: 99 ⬆️ 3.1% 💲 Median Sale Price:$180,000 ⬆️ 9.0% 💵 Average Sale Price:$201,783 ⬇️ 15.9% ⏳ Days on Market: 33 ⬇️ 34.0% 🏷️ List Price Received: 98.4% ⬆️ 0.7% 📦 Homes for Sale: 323 ⬆️ 18.3% 📈 Months of Inventory: 4.0 ⬆️ 14.3%
📅 2026 YEAR-TO-DATE vs. 2025
🏠 New Listings: 820 ⬆️ 7.6% ✍️ Pending Sales: 572 ⬇️ 1.9% 🔑 Closed Sales: 488 ⬆️ 3.6% 💲 Median Sale Price:$178,500 ⬆️ 14.1% 💵 Average Sale Price:$213,242 ⬇️ 0.3% ⏳ Days on Market: 49 ➖ No Change 🏷️ List Price Received: 97.1% ⬆️ 0.6%
🔎 OUR TAKE — CHAUTAUQUA COUNTY
The Chautauqua County market continues to show solid strength while gradually becoming more balanced.
The number that stands out is the 14.1% year-to-date increase in median sale price, while closed sales are also up 3.6%. At the same time, inventory has increased 18.3%, giving buyers considerably more choices than they had during the extremely tight markets of the past few years.
July was particularly active. Pending and closed sales both increased, homes that sold moved significantly faster, and sellers received an average of 98.4% of their most recent asking price.
One interesting contrast is the July average sale price, which dropped 15.9%, while the median increased 9.0%. That's a good reminder that one month's average can be heavily influenced by the mix of properties that happen to close. The stronger 14.1% year-to-date median increase gives us a better indication of the overall direction of home values.
Bottom line: Buyers have more choices, but desirable homes that are properly priced are still selling. For sellers, pricing and presentation remain critical as inventory continues to grow.
📍 CATTARAUGUS COUNTY
📊 July 2026 vs. July 2025
🏠 New Listings: 110 ⬆️ 44.7% ✍️ Pending Sales: 47 ⬇️ 20.3% 🔑 Closed Sales: 70 ⬆️ 6.1% 💲 Median Sale Price:$205,000 ⬆️ 24.6% 💵 Average Sale Price:$226,244 ⬆️ 2.1% ⏳ Days on Market: 43 ⬆️ 26.5% 🏷️ List Price Received: 96.5% ⬇️ 2.2% 📦 Homes for Sale: 261 ⬆️ 15.5% 📈 Months of Inventory: 4.7 ⬆️ 11.9%
📅 2026 YEAR-TO-DATE vs. 2025
🏠 New Listings: 590 ⬆️ 14.6% ✍️ Pending Sales: 411 ⬆️ 6.5% 🔑 Closed Sales: 349 ⬆️ 1.7% 💲 Median Sale Price:$180,000 ⬆️ 2.6% 💵 Average Sale Price:$222,078 ⬇️ 0.1% ⏳ Days on Market: 63 ⬆️ 10.5% 🏷️ List Price Received: 95.9% ⬇️ 0.8%
🔎 OUR TAKE — CATTARAUGUS COUNTY
Cattaraugus County is showing clearer signs of a more balanced and price-sensitive market.
July's 24.6% increase in median sale price looks impressive, but the year-to-date median is up a much more modest 2.6%, while the average sale price is essentially unchanged. That tells us not to put too much weight on one month's price movement.
The bigger story is inventory. New listings surged 44.7% in July, homes for sale increased 15.5%, and inventory reached 4.7 months. Buyers have more options and don't necessarily have to jump on the first property they see.
July pending sales fell 20.3%, homes took longer to sell, and sellers received 96.5% of their most recent asking price. Those are signs that buyers are becoming more selective and have greater negotiating leverage.
Bottom line: The market remains active—closed sales are still ahead of last year—but sellers need to be realistic about price and condition. Buyers, meanwhile, are finally seeing more selection and negotiating opportunities.
🏠 Thinking About Buying or Selling?
County-wide statistics are useful for understanding the overall market, but real estate is local—sometimes right down to the neighborhood, street and individual property.
If you're thinking about selling, or you're simply curious about what your home could realistically sell for in today's market, we'd be happy to provide a complimentary, no-obligation market analysis.
Just reply to this email or give us a call.
Rick & Julia McMahon Broker Associates & Partners Real Estate Advantage
This past week, a ribbon was cut and the county officially announced
that the Sewer Extension Phase II for the West Side of Chautauqua Lake
is now ready for hook-ups.
If this had been a church setting, you might have been tempted to
shout "Hallelujah!" or "Amen!" but, in any event, it was an important
occasion.
I don't think that the general public realizes what it takes to
bring such a large project of this type to fruition. A Sewer District
expansion requires the approval of the municipalities involved. It also
requires the creation of or expansion of sewer district boundaries and
all of the legal requirements that entails.
Next, of course, comes financing. The State Comptroller will not
approve any of this unless the district is "affordable," and that means
that millions of dollars in state and federal assistance were required.
The County, to its credit, designated funds from Washington–those
generated by the Bipartisan Infrastructure Law which was enacted in
response to the last economic downturn--to be invested in this important
health/environmental improvement project on Chautauqua Lake. Funding
from the state's Environmental Facilities Corporation also contributed
substantially to the project.
Then, of course, the project had to be designed and engineered,
needed to be bid, the bid awarded, various highway and environmental
permits granted…all of this before a shovel full of dirt could be moved
or a pipeline laid.
The good news in terms of financing is that Phase II construction
costs came in at $4 million less than had been projected, thus
substantially reducing the annual homeowner fees that will be charged.
(The annual cost for sewer service includes operating costs as well as
the debt service on the local share needed to complete construction.)
Many worked to bring Phase II to a successful conclusion, but special
recognition should be given to County Legislator and Legislative
Chairman, Pierre Chagnon, who has been directly involved in getting
sewers built around Chautauqua Lake for the past 40-50 years. He has
understood, through experience, that something like sewer construction
takes a long time and requires a lot of work in order to be completed.
Kudos also to all of the other public officials involved and Sewer
District employees for their persistence in getting this done.
This new section of sewers (as are most around the lake)
is a pressurized system where pumps and pumping stations are required.
This means electricity is also needed. Workers at Cummins will be
interested to know also that backup generation at the major pump station
locations will be powered by Cummins natural gas engines.
The Sewer District is responsible for maintaining, providing the
electricity for, and then installing the various pumps and pump grinders
which are a part of the system. Landowners are responsible for the
connection going from their house to the nearby pump grinder.
It is time now for residents from Stow to Prendergast Point to engage
an approved contractor to make these connections from their home to the
new sewer.
But, back to the achievement--thanks again to all of the Sewer
District personnel, public officials, the contractors and workers on the
job who got us to this point. Thanks also from Chautauqua Lake-- it
will be a prime beneficiary of this work!
Rolland Kidder is a Stow resident.
For More Information On Chautauqua Lake & County Real Estate and Living Visit: chautauqualakehomes.com
As we move through the heart of the summer selling season, the housing markets in Chautauqua and Cattaraugus Counties continue to evolve. Here's a quick snapshot of what's happening locally and what it means if you're thinking about buying or selling.
🏡 Chautauqua County
June vs. June 2025
🏠 New Listings:157 ▲ 9.8%
✍️ Pending Sales:109 ▲ 7.9%
🔑 Closed Sales:86 ▼ 1.1%
💲 Median Sale Price:$185,107 ▲ 9.0%
💵 Average Sale Price:$234,080 ▲ 11.9%
⏳ Days on Market:58 ▲ 34.9%
📦 Homes for Sale:307 ▲ 26.9%
Year-to-Date
🏠 New Listings:666 ▲ 8.5%
✍️ Pending Sales:467 ▼ 3.7%
🔑 Closed Sales:389 ▲ 3.7%
💲 Median Sale Price:$176,582 ▲ 16.2%
💵 Average Sale Price:$216,166 ▲ 4.4%
📍 Our Take
Chautauqua County continues to demonstrate a healthy and resilient market. Home values remain strong, with the median sale price climbing 16.2% year-to-date, while closed sales have also increased despite today's higher interest rates.
Inventory has grown significantly, giving buyers more choices than they've had in several years. Although homes are taking longer to sell, properly priced properties—especially those in desirable locations—continue to attract solid buyer activity.
The market is gradually shifting from the extreme seller's market we've experienced over the past few years toward a healthier, more balanced market that benefits both buyers and sellers.
🏡 Cattaraugus County
June vs. June 2025
🏠 New Listings:103 ▼ 8.8%
✍️ Pending Sales:81 ➖ No Change
🔑 Closed Sales:45 ▼ 6.3%
💲 Median Sale Price:$169,450 ▼ 5.2%
💵 Average Sale Price:$198,907 ▼ 5.9%
⏳ Days on Market:70 ▲ 45.8%
📦 Homes for Sale:222 ▼ 1.3%
Year-to-Date
🏠 New Listings:480 ▲ 9.3%
✍️ Pending Sales:359 ▲ 9.8%
🔑 Closed Sales:279 ▲ 0.7%
💲 Median Sale Price:$175,750 ▼ 1.0%
💵 Average Sale Price:$221,044 ▼ 0.6%
📍 Our Take
Cattaraugus County remains a steady, balanced market, although buyers have become more selective. Pending sales are nearly 10% higher year-to-date, indicating demand remains healthy, but buyers are placing greater emphasis on condition, pricing, and value.
Home prices have leveled off slightly compared to last year, and homes are taking longer to sell. Sellers who price their homes competitively and present them well are still achieving successful results, while overpriced listings are spending considerably more time on the market.
For buyers, this means more opportunities and negotiating room. For sellers, today's market rewards realistic pricing and strong marketing more than ever.
Thinking About Buying or Selling?
Every home—and every neighborhood—has its own story. County statistics provide a great overview, but they don't determine the value of your property.
If you're curious what your home could sell for in today's market, We'd be happy to prepare a complimentary, no-obligation market analysis based on recent sales in your neighborhood.
Simply reply to this email or give me a call.
Rick & Julia McMahon Broker Associates & Partners
Real Estate Advantage
Home
insurance provides protection against major losses and is required for
most mortgages, making it a core part of the cost of homeownership and
the housing finance system.
Rising premiums can meaningfully
affect affordability because higher insurance costs add to monthly
housing expenses; for example, a $400,000 home’s annual insurance cost
could increase from about $3,000 to nearly $4,000.
Insurance
costs vary widely by location and can change over time as rebuilding
expenses, home values, and weather-related risks increase, reducing
purchasing power in some housing markets more than others.
The
first time many homeowners really notice their insurance isn’t when
they buy the policy — it’s when the renewal notice arrives.
The
home hasn’t changed. The mortgage payment hasn’t changed. But the
insurance premium has gone up, sometimes noticeably. What used to feel
like a routine, background expense suddenly feels like part of the cost
of living in that home.
That shift is subtle, but important. Home
insurance has always been part of the cost of owning a home, but it’s
becoming harder to ignore just how much it matters.
At its most basic level, home insurance protects you against
large, unpredictable losses. Fire, storms, theft — events that are rare
but financially devastating when they occur.
Instead of bearing
that risk all at once, homeowners pay a predictable annual premium.
Insurance turns uncertainty into something manageable.
But there’s a second reason insurance matters: Your lender requires it.
When
you borrow to buy a home, the house itself is the lender’s backup plan.
If something goes wrong and you can’t keep making payments, the lender
can recover value by selling the home. Insurance makes sure that backup
plan still works, even if the home is damaged or destroyed.
That’s
why insurance is effectively mandatory in most transactions. It doesn’t
just protect the homeowner. It helps support the structure of mortgage
lending itself.
When a small percentage becomes a real number
For many years, insurance was a relatively quiet part of the
homeownership equation. It didn’t disappear, but it rarely drove
decisions.
That’s changed — not because insurance is new, but because the numbers involved have grown.
Premiums
have been rising, and home values have increased. When you apply even
modest rates to much larger asset values, the dollar impact becomes more
noticeable.
Source: Homes.com
Consider a simple example. A home worth $400,000 might
have cost about $3,000 per year to insure not long ago. At somewhat
higher rates, that number can move closer to $4,000.
That extra $1,000 per year — about $80 per month — may not seem dramatic on its own. But it doesn’t exist in isolation.
It arrives alongside higher mortgage rates, higher property taxes and higher home prices. Together, those pressures add up.
Because
buyers think in terms of monthly payments, even incremental increases
matter. That additional cost may not disqualify a buyer entirely, but it
can reduce what they can borrow by a meaningful amount.
Insurance, in that sense, functions a lot like an interest rate: It quietly determines how much home a buyer can afford.
Why location plays such a large role
Unlike mortgage rates, which are broadly national, insurance is intensely local.
The reason is simple: Insurance prices reflect expected losses. And expected losses depend on risk.
In some regions, that risk comes from hurricanes or flooding. In others, wildfires. In others still, tornadoes or severe storms.
These risks aren’t evenly distributed — and neither are the costs.
Two
homes with similar prices can have very different insurance premiums
depending on where they’re located. In higher-risk areas, insurance can
cost several times as much as in lower-risk regions.
That creates a
new layer of variation in housing affordability. It’s not just about
prices and interest rates anymore. It’s also about exposure to physical
risk — and how that risk is priced.
In some cases, the question
goes beyond cost. If insurance becomes difficult to obtain at any
reasonable price, it can limit the ability to finance a home altogether.
The part of housing costs that doesn’t stay fixed
There’s another important difference between insurance and most other housing costs: It can change over time.
A
fixed-rate mortgage gives borrowers predictability. Property taxes may
adjust, but often gradually. Insurance, by contrast, is reassessed
regularly.
As risks evolve — or as the cost of rebuilding changes — premiums can increase.
That means part of the cost of owning a home is effectively adjustable.
A
buyer may choose a home based on today’s total monthly payment, only to
find that one component of that payment — insurance — moves over time.
This
introduces a different kind of uncertainty into homeownership,
especially in areas where risks are changing or becoming more
concentrated.
What’s pushing premiums higher
The basic economics are straightforward: When expected costs rise, insurance prices follow.
Rebuilding costs have increased. Materials and labor are more expensive than they were a decade ago, raising the cost of claims.
Home values have risen as well. Insurers are covering more valuable assets, which increases potential losses.
And in some regions, weather-related risks are playing a larger role, increasing both the frequency and severity of claims.
These forces reinforce one another. Higher-value homes in higher-risk areas are particularly expensive to insure.
The result is steady upward pressure on premiums, even if the changes from year to year feel gradual.
A quieter but important shift in affordability
Affordability is ultimately about the total monthly payment.
Mortgage
principal and interest are the largest component, but they are not the
only one. Property taxes, maintenance and insurance all contribute to
the full cost of owning a home.
As insurance becomes more expensive, it takes up a larger share of that total.
For
a buyer working within a fixed budget, that shift has a direct
consequence: less room for the mortgage itself, and therefore a lower
maximum home price.
This mechanism operates quietly, but consistently. When insurance costs rise, purchasing power falls.
Because
insurance varies by location, that effect is uneven. It can weigh much
more heavily on some regions than others, even if home prices themselves
move in similar ways.
Seeing housing through a wider lens
For a long time, conversations about housing affordability focused primarily on home prices and mortgage rates.
Those factors still matter enormously. But they aren’t the whole picture.
Insurance
connects housing markets to physical risk in a direct way. It
translates geography — flood zones, fire risk, storm exposure — into a
recurring cost.
That makes it part of the price of housing in a deeper and more dynamic sense than many people realize.
A different way to think about insurance
Home insurance used to feel like protection against rare events — important, but mostly in the background.
It still plays that role. But it also does something just as important: It helps determine what it actually costs to own a home.
That reality doesn’t show up all at once. It shows up slowly, renewal by renewal, premium by premium.
But
over time, it changes how housing markets work — shaping not just what
homes are worth, but where people can realistically afford to live.
Brad Case, PhD, CFA,
CAIA, has more than 35 years of experience in the real estate industry,
including positions as an economist with the Federal Reserve Board,
Nareit, Fannie Mae and Middleburg Communities.
Research
Specialist for the Darrin Fresh Water Institute at Rensselaer
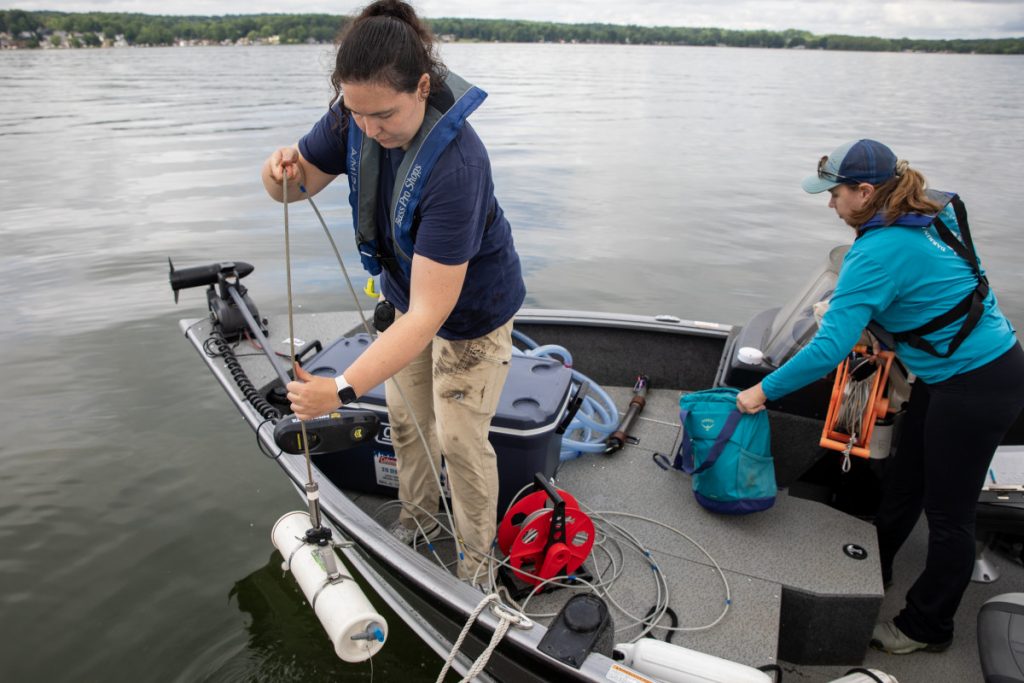
Polytechnic InstituteKira Yerofeev, left, collects data with fellow
Research Specialist Allison Hrycik using a Van Dorn water sampler.
SKYLAR SEAVEY / STAFF PHOTOGRAPHER
JENNA OUTCALT Staff Writer
The best part of Allison Hrycik’s and Kira Yerofeev’s job is being
outdoors. The two scientists go out on Chautauqua Lake every other week
in a boat brimming with scientific instruments as part of The Jefferson
Project, a research endeavor entering its sixth year on Chautauqua Lake.
Their equipment ranges from tools that scientists have relied on for
over a century to cutting-edge sensors that take samples of lake water.
Hrycik, who has been on the project for three years, is a research
scientist focusing on algae ecology for the Darrin Fresh Water Institute
at Rensselaer Polytechnic Institute. She and Yerofeev, a research
specialist from Rensselaer Polytechnic Institute in her second year on
the project, take samples from the lake year-round, even when they have
to go through ice in the winter. They are collecting massive amounts of
information on the ecology of the lake, much of it focusing on when and
where harmful algae blooms occur.
Why is Chautauqua Lake the right place for this research?
“A lot of algae,” Hrycik said simply.
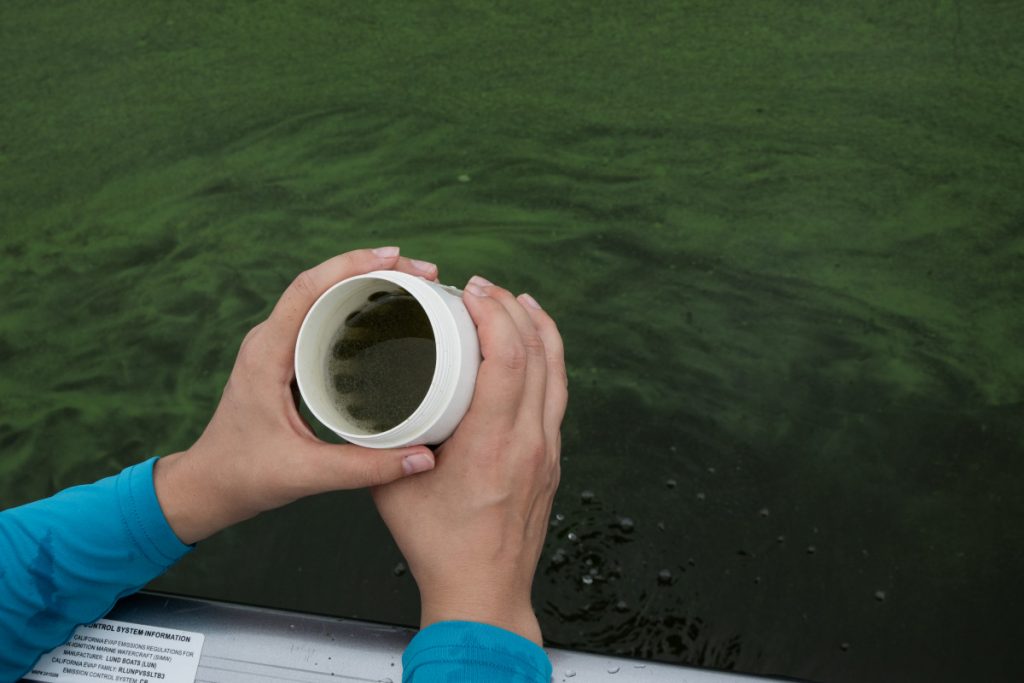
Research
Specialist for the Darrin Fresh Water Institute at Rensselaer
Polytechnic Institute Allison Hrycik lifts a sample cup from the water
of Chautauqua Lake Tuesday. SKYLAR SEAVEY/STAFF PHOTOGRAPHER
Boaters and swimmers may have already noticed bright green areas in
the lake. That color comes from the cyanobacteria that make up algae
blooms, some of which can be toxic to humans and animals. These blooms
become more common when nutrients like phosphorus and nitrogen run off
into the lake.
The Jefferson Project and State University of New York at Fredonia
are conducting research on the lake, investigating what encourages algae
and plant growth. On July 1, Hrycik and SUNY Fredonia professor
Courtney Wigdahl-Perry gave an update on the information they gathered
throughout last year.
Wigdahl-Perry explained during the research update that cyanobacteria are naturally found in the lake.
“They’re supposed to be here. But when the system gets out of
balance, we could create more opportunities for the cyanobacteria to
really grow and proliferate,” she said, “And most of the time, those
causes are due to human activity.”
Nutrient runoff can come from agricultural or residential
fertilizers, decomposing plant matter at the bottom of the lake and
stormwater that picks up nutrients from surrounding land and deposits it
in the lake. Impervious surfaces such as pavement allow more nutrients
to continue into the water, where grass or wetlands could have absorbed
them. The Jefferson Project is monitoring six tributaries that deposit
into the lake to see where the most nutrients are coming from so it can
guide mitigation efforts in the future.
However, other factors can play into algae growth in the lake as
well. Algae, like plants, grows faster with more warmth and sunlight.
This makes it more present in shallower parts of the lake, such as the
south basin, where the average depth is only 11 feet compared to the
north basin’s average depth of 26 feet.
Warmth and sunlight also encourage the growth of aquatic weeds in the
lake. Chautauquans who visited in 2025 might have noticed an excess of
weeds; the lake failed to freeze over in the 2024–2025 winter, allowing
the plants to proliferate in the spring and summer. The freeze this
winter indicates less severe overgrowth during this season.
SUNY Fredonia student Mayc Kelley spent last year investigating
differences in algae growth based on vertical position in the lake.
During the research update, Wigdahl-Perry said Kelley’s research
confirmed that algae communities differed by depth. Some of the
variation is due to temperature, but Wigdahl-Perry said they are looking
forward to more research to determine other factors, such as the amount
of light and nutrients at different depths.
Emma Steffenhagen, another SUNY Fredonia student, studied the
relationship between algae and different types of aquatic plants to see
if their relationship was mutually beneficial or competitive. Her
research showed that there is no major difference between algae growth
around native versus invasive plants, allowing future studies and
mitigation efforts to look at the physical structure that plants provide
for algae growth rather than focusing on species.
Wigdahl-Perry said the goal of the research was not to “purify” the
lake, but rather to encourage its natural ecology to thrive and mitigate
imbalance from human activities.
“We’re here to understand how the natural system works and to work
within what we can do to get us back to a more natural state, where
there are checks and balances biologically,” she said.
Hrycik presented on the Jefferson Project’s progress. Last year was
the project’s biggest year for funding and sampling, with 14 survey
sites on the lake. This year, there are only five survey sites on the
lake, but there will be a greater focus on the tributary monitoring
stations, where nutrients are entering the lake.
Design by Laura Quisenberry / Design Editor
Two of the five stations have vertical profilers, floating stations
that reach downward into the lake and take up to four measurements per
second through the whole water column. The Jefferson Project is also in
the process of adding two weather monitoring stations to their system,
according to Hrycik during the research update. The project can then use
computer modeling to marry data from the lake, watersheds and weather.
“This can help us build a more complete picture of lake processes and
then help us forecast what’s going on if something changes over time,”
Hrycik said in the update.
At the lake survey stations, Hrycik and Yerofeev test for visibility,
zooplankton content, temperature and more. The information helps them
study where algae blooms occur most often and where they might occur
next. According to the research update, The Jefferson Project will make
all of its 2025 data public. This year, the funding for the project is
coming from the state of New York rather than fundraising, so data will
have to go through a more arduous review process by the state before
it’s published.
Hrycik explained that The Jefferson Project was mainly focused on
research, not local action plans. For mitigation plans, the project has
to utilize local partners such as Everwild Land Trust, the organization
spearheading an upcoming engineered wetland project.
The Jefferson Project’s research discovered that more nutrients flow
into the lake at the very beginning of a storm than any other time. The
project is helping Everwild Land Trust engineer a way to ensure the
wetland can absorb the influx of runoff at the start of storms.
Wigdahl-Perry and Hrycik also mentioned smaller mitigation projects
around the Institution during the research update, such as pervious
pavement that allows nutrients to seep into the ground rather than
continue into the lake and support for natural plants that can absorb
extra nutrients.
Hrycik explained that people often want a silver bullet to “cure” the
lake, but in reality, the pace of recovery is a little slower. However,
researchers working with the lake, as well as the community around it,
are committed to helping Chautauqua Lake recover to its natural state.
“There’s a lot of things we can do, but it’s going to be little things that add up over time,” Hrycik said.
For More Information On Chautauqua Lake & County Real Estate and Living Visit: chautauqualakehomes.com